Business Loan
Explore funding for eligible business expansion, operations and growth requirements.
Explore Loan
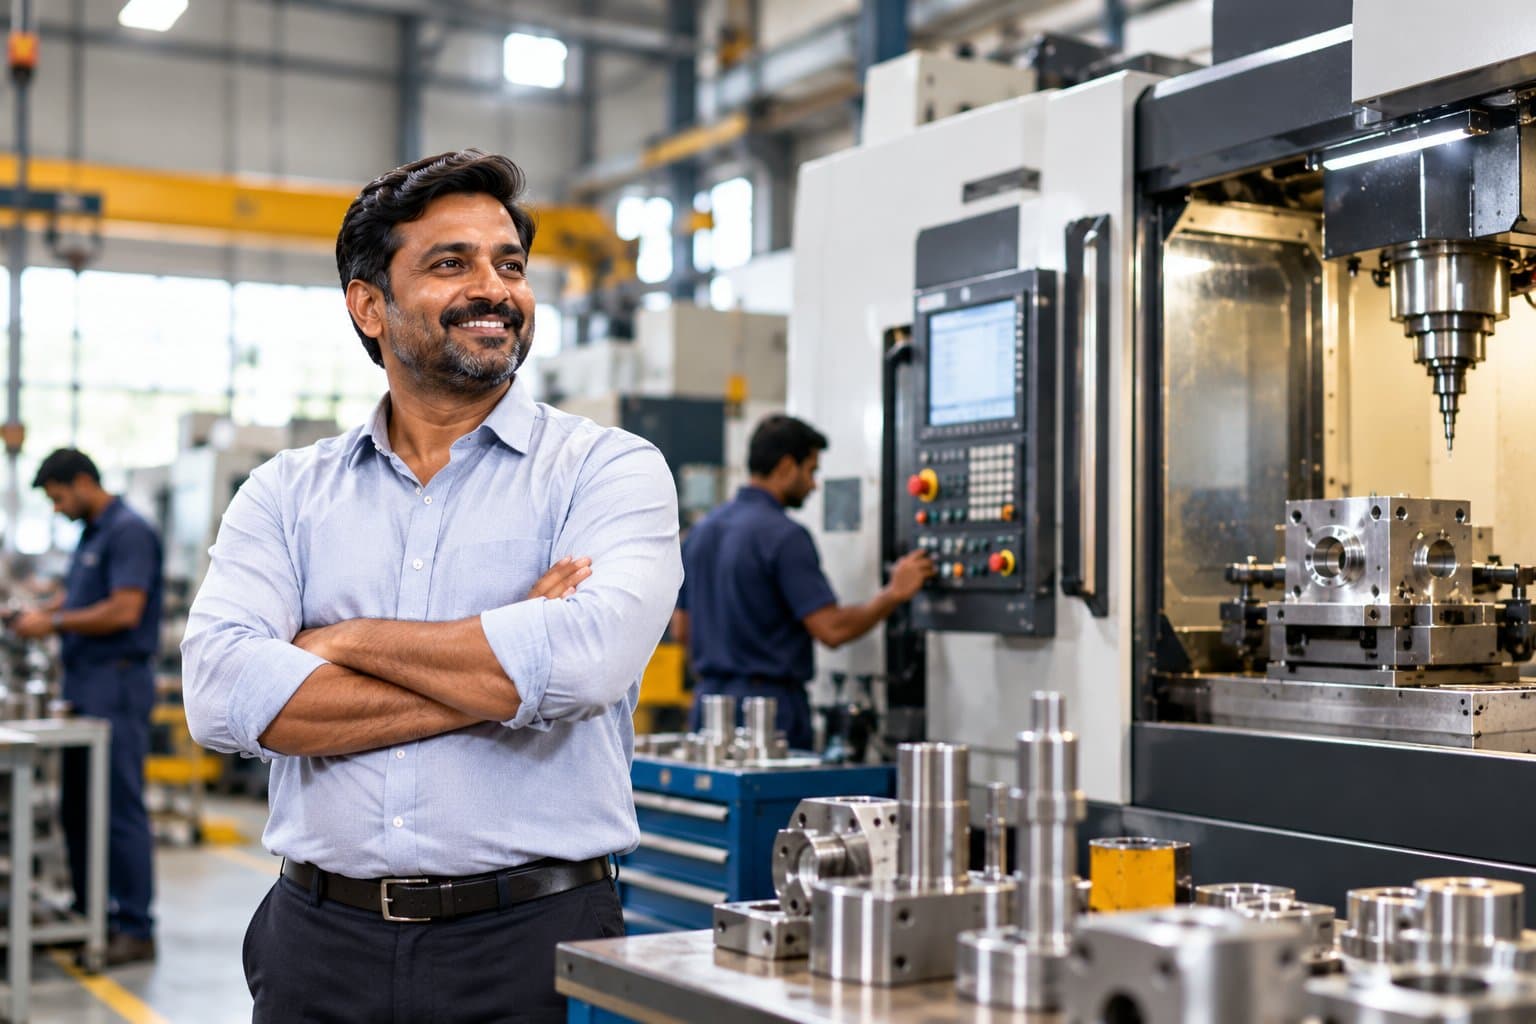
Explore financing for new production machinery, equipment upgrades and capacity expansion. We help you understand the options and prepare a well-documented application — the lender assesses it and makes the credit decision.
Use cases
Buy additional machines to take on larger orders or new product lines.
Replace older machinery to improve output quality, uptime and efficiency.
Invest in CNC, packaging, testing or material-handling equipment.
Equip your unit for the specifications of a new customer or tender.
Lenders weigh these and other factors according to their own credit policies.
Indicative only — the exact list depends on the lender, your constitution and the proposal.
The process
Tell us about the machine, its cost and how it fits your production plans.
We discuss the financing routes that may suit your profile and the machinery involved.
We help you organise financials, KYC and the supplier quotation.
The lender evaluates the proposal — this may include a site visit or technical review.
If sanctioned, disbursal follows the lender's terms, often paid directly to the supplier.
Eligibility, approval, pricing, collateral requirements and disbursal depend on the lender and its applicable policies. LoanDhara does not lend and does not guarantee approval.
Lenders commonly take a charge (hypothecation) on the financed machinery. Some may also ask for additional collateral or guarantees, or consider CGTMSE cover for eligible micro and small enterprises. This depends on the lender's policy and your profile.
Some lenders consider used machinery, usually with an independent valuation and different terms. Many prefer new equipment from established suppliers. It is worth raising this early in the conversation.
Lenders usually finance a portion of the cost and expect you to contribute the balance as margin. The proportion depends on the lender, the machinery and your business profile.
More questions? See all FAQs or talk to an expert.
Share your requirement and we’ll help you understand the next financing step.
Explore funding for eligible business expansion, operations and growth requirements.
Explore LoanUnderstand eligible collateral-free credit facilities backed by the applicable credit guarantee framework.
Explore Loan