Machinery Loan
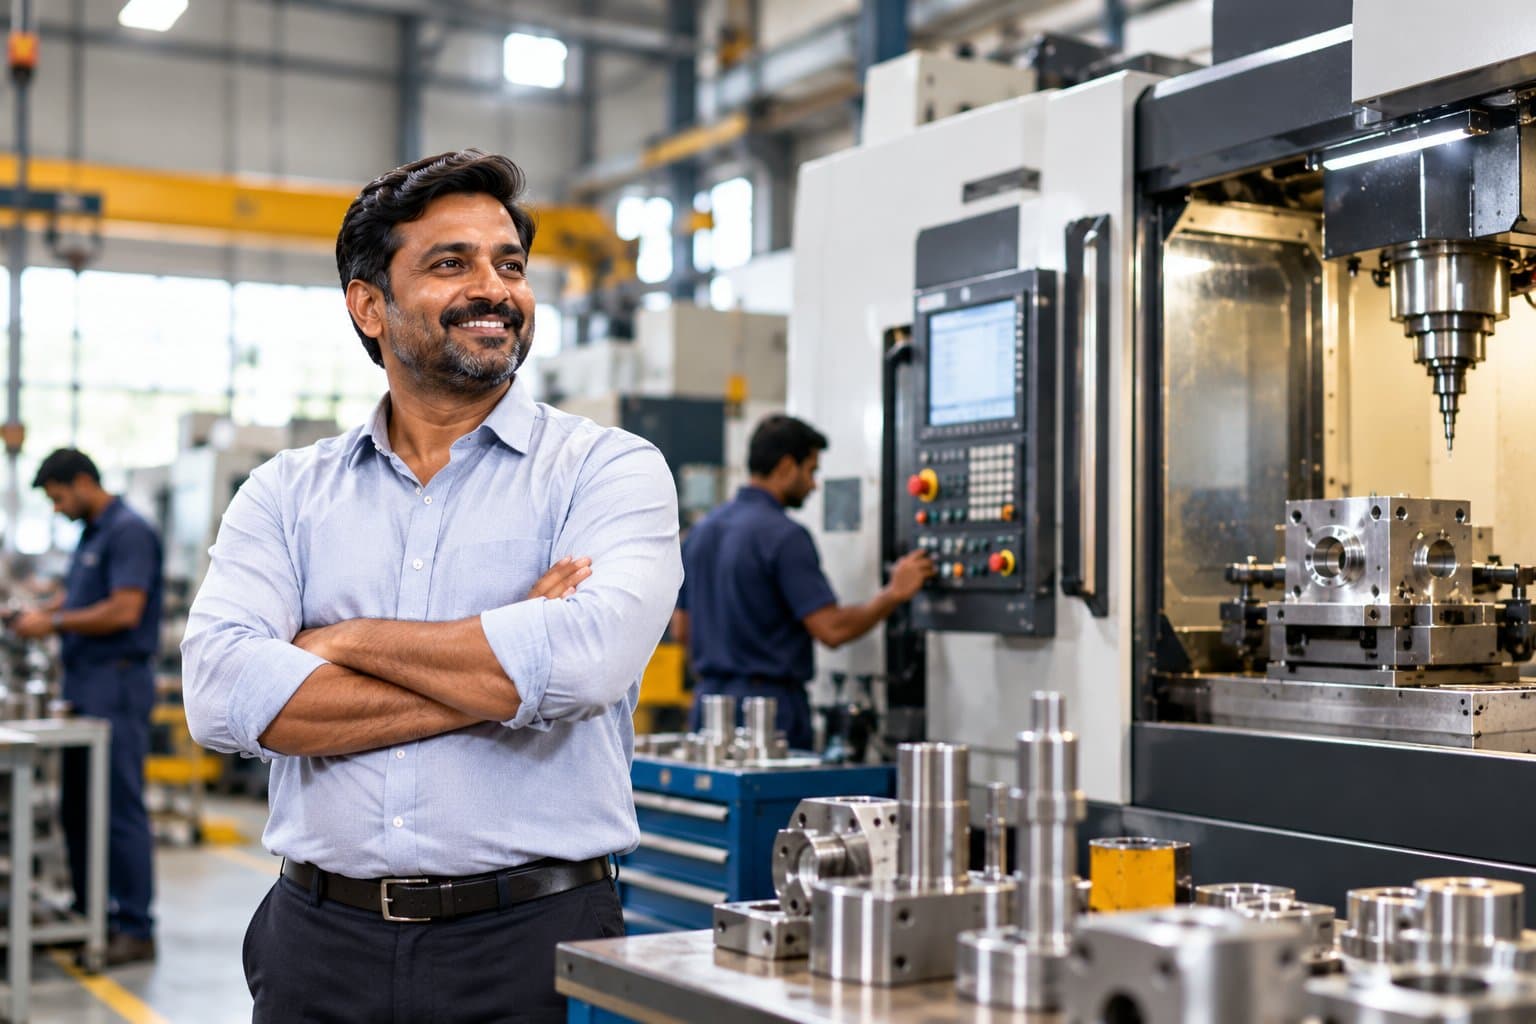
Finance eligible machinery and production equipment to expand or modernise your operations.
Explore Loan
Business loans for India's growing enterprises
LoanDhara helps Indian SMEs and MSMEs explore suitable business financing options from banks and NBFCs, with guidance throughout the application journey.
Our team
Our team brings experience from banking and financial services to help Indian SMEs and MSMEs navigate business financing.
A team with prior experience in banking and financial services.
Practical understanding of how lenders typically appraise MSME credit.
Focused on manufacturers, traders, service firms and transporters.
Clear explanations of options, documents and next steps.
Loan products
From managing cash flow to expanding operations, explore financing options designed around your business needs.
Finance eligible machinery and production equipment to expand or modernise your operations.
Explore Loan
Explore funding for eligible business expansion, operations and growth requirements.
Explore Loan
Manage inventory, supplier payments, operating expenses and everyday cash-flow needs.
Explore Loan
Explore working-capital facilities for managing eligible short-term business funding needs.
Explore Loan
Explore financing for eligible commercial vehicles used in business operations.
Explore Loan
Understand eligible collateral-free credit facilities backed by the applicable credit guarantee framework.
Explore LoanWhy LoanDhara
Guidance informed by practical knowledge of lending processes.
Explore relevant financing options from participating banks and NBFCs.
Understand the documents and information lenders may require.
Get assistance as your application progresses.
How it works
Step 1
Tell us about your business and funding needs.
Step 2
Review financing routes that may fit your business profile.
Step 3
Receive guidance on documents and application requirements.
Step 4
The relevant lender evaluates the application and makes the credit decision.
Eligibility, approval, pricing, collateral requirements and disbursal depend on the lender and its applicable policies. LoanDhara does not lend and does not guarantee approval.
Who we work with
From factory floors to retail counters and highways — guidance shaped around how your sector actually runs.
Illustrative scenarios
How we approach common financing situations. These are illustrative examples, not customer testimonials or results.
FAQs
Straight answers to common questions about business financing in India.
You can explore machinery loans, business term loans, working capital loans, cash credit and overdraft (CC/OD) facilities, commercial vehicle loans and CGTMSE scheme-linked financing. The products actually available to you depend on the lenders involved and your business profile.
Proprietorships, partnerships, LLPs and private limited companies engaged in manufacturing, trading or services can usually approach lenders for business finance. Each lender sets its own criteria — typically covering business vintage, turnover, profitability, banking conduct and credit history. Udyam Registration is often helpful and is required for some MSME-specific schemes.
Lenders commonly ask for KYC of the business and promoters, Udyam and GST registration where applicable, income tax returns and financial statements for recent years, business bank statements and details of existing loans. Product-specific documents — such as machinery quotations or stock statements — may also be requested. Requirements vary by lender.
Some lenders consider new businesses, especially with a clear project report, promoter experience and an appropriate contribution or security. Options are usually narrower than for businesses with an operating track record. Schemes such as CGTMSE may be relevant for eligible new micro and small enterprises, subject to the lender's appraisal.
A machinery loan helps fund the purchase of eligible equipment. You typically share a supplier quotation, contribute a portion of the cost, and the lender — if it sanctions the loan — often pays the supplier directly and takes a charge on the machine. You repay in instalments over an agreed tenure.
A term loan funds longer-term needs such as machinery, expansion or premises and is repaid in instalments over a fixed tenure. Working capital finance supports day-to-day operations — inventory, receivables and expenses — and is often structured as a revolving limit that is reviewed periodically.
Cash credit (CC) and overdraft (OD) are revolving facilities that let you draw funds up to a sanctioned limit and repay as cash comes in. CC is usually secured by stock and receivables, with usable funds linked to your drawing power; OD is often secured by other assets such as property or deposits. Interest is generally charged on the amount used, along with any charges in the lender's terms.
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) was set up by the Government of India and SIDBI. It provides credit guarantee support to eligible member lending institutions for collateral-free loans to eligible micro and small enterprises, under the scheme rules in force. CGTMSE is not a lender — you apply to a participating bank or institution, which appraises your loan.
It varies with the lender, the product, the loan amount and how complete your documents are. Larger or secured proposals may involve valuations, legal checks or site visits that take longer. We cannot promise timelines, but a well-prepared application helps avoid avoidable delays.
No. LoanDhara is not a lender. We help you understand options and prepare your application, but eligibility, approval, interest rates, collateral requirements and disbursal are decided solely by the lender under its policies.
Tell us what your business needs. We’ll help you explore the next financing step.